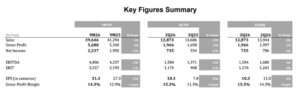
● 9M26 net income reached P2.2 bn, up 15% YoY; 3Q26 net income reached P735 mn, up 32% YoY
● Food Ingredients delivered a significant earnings improvement, with 9M26 earnings rising 77% YoY as margins continued to recover
● Blended gross margins rose 1.4 ppts, driven by HMSP and commodities, with HMSP accounting for 51% of sales
● FCF maintained its positive streak at P1.9 bn as at 9M26 with lower capex and easing commodity prices;
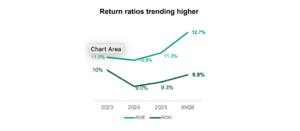
● Return ratios continued to improve, with ROE at 12.7% and ROIC at 9.8%, up 1.4 ppts and 0.5 ppt, respectively, from FY25 levels
Management perspective and outlook
“While the business environment continues to be challenged by unresolved geopolitical tension, local inflationary pressure, coupled with a depreciating peso and higher interest rates, the company was able to post earnings growth of 15% for the first nine months of 2026,” remarked D&L President & CEO Alvin Lao.
“D&L’s diversified business segments have allowed us to ride out these external pressures and focus on servicing our customers with high value, specialty products anchored on our R&D DNA. We are pleased to see our Food Ingredients business continuing to deliver a significant turnaround in 3Q26, with a 77% jump in earnings and 2.7 ppts in margin improvement. Through our technical capabilities, we are able to weather headwinds, and allow us to ensure supply reliability and continuity for our customers, elevating us to preferred supplier status and solidifying our competitive position further,” Lao added.
“The continued normalization and relief from elevated coconut oil prices allows us to optimize our working capital requirements. Improved operating cashflows also allowed us the full redemption of our P2.0bn Series B 5-year bond, upon its maturity last September 14, 2026, insulating us from heightened interest rate pressures,” Lao continued. “Our long term business outlook remains stable and unwavering. With raw material costs continuing to stabilize and our ongoing product portfolio optimization initiatives, we remain optimistic about D&L’s ability to deliver more resilient and improved profitability moving forward.
This confidence is reflected in the continued share purchases by Jadel Holdings, the Lao family’s holding company, which has increased its stake in D&L by approximately 4.5% since the pandemic. In 2025 and year-to-date 2026 alone, Jadel acquired approximately 106 million and 12 million shares, respectively. At current levels, the stock continues to offer an attractive dividend yield of approximately 7%, based on dividends declared this year,” Lao added.
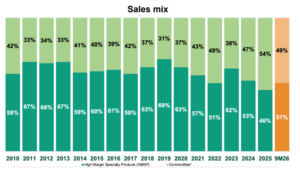
Sales mix tipped towards HMSP 51% of sales, with its margins up by 2.4 ppts YoY for 9M26
The sales mix shifted back in favor toward High Margin Specialty Products (HMSP), which accounted for 51% of revenues in 9M26. Over the past few years, the sales mix had leaned towards commodity sales, driven by the higher biodiesel blending mandate. As the company harnessed its R&D and technical capabilities to develop higher margin specialty products, management expects HMSP to contribute an increasingly larger share of the mix over time.
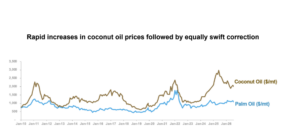
The stabilization of coconut oil prices—one of our key raw materials—at around USD 2,000/MT, following a prolonged period of volatility, supported margin recovery in 9M26. This margin recovery was particularly visible in the High Margin Specialty Products (HMSP) segment, where gross profit margins (GPM) expanded by 2.4 percentage points YoY during the period, reflecting the ability to price-pass through, further easing input cost pressures.
Meanwhile, D&L’s export business, backed by the new Batangas plant facility, continues to contribute 23% of total sales, with HMSP exports up 14% YoY, providing the company a natural hedge against its US-denominated imported raw material costs amid the weakening peso.
“While the weakening peso benefits our export business by enhancing our competitiveness and supporting market diversification, the continued growth of our exports also provides a natural hedge against our foreign currency exposure from imported raw materials. This further complements our specialty products strategy, allowing us to pass on pricing adjustments while
preserving margins,” added Lao.
Free Cash Flow (FCF) swings positive to P1.9bn for 9M26
Free cash flow turned positive at P1.9 billion for the period, primarily driven by lower incremental working capital requirements as coconut oil prices continued to normalize, boosted further with muted capital expenditures. Barring any significant commodity price shocks or substantial working capital requirements, the company expects free cash flow to remain positive. With free cash flow expected to remain positive and capex staying at normalized levels, the company is well positioned to continue deleveraging its balance sheet.
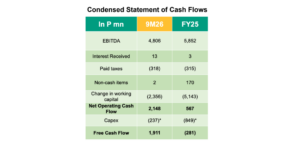
Meanwhile, the company’s balance sheet remained solid despite the significant capital investments and unprecedented rise in commodity prices over the past few years. Debt-to-EBITDA improved to 4.0x in 9M26 from 4.3x in FY25, reflecting stronger earnings and improved cash flow generation. Interest coverage likewise strengthened to 3.6x from 3.2x over the same period.
Return ratios continue to improve
Amid a challenging operating environment, the company delivered continued growth, driving further improvement in return ratios. ROE rose to 12.7% (+1.4 ppts vs end-2025), while ROIC increased to 9.8% (+0.5 ppt vs end-2025). As the Batangas plant ramps up and contributes more meaningfully to earnings, return ratios are expected to continue improving.
Segment Results
Food Ingredients
The Food Ingredients segment delivered a strong earnings performance in 9M26, with earnings increasing 77% YoY, largely driven by a 2.7-ppt expansion in margins. This improvement was supported by more stable coconut oil prices and a more profitable product mix following the company’s SKU rationalization initiatives. As these initiatives continue to gain traction and raw material costs stabilize further, the segment is well positioned to sustain its earnings momentum and deliver more consistent profitability in the periods ahead.
Chemrez
Following a banner year in 2025, when earnings nearly doubled, Chemrez’s earnings moderated by 27% YoY in 9M26, reflecting a normalization in demand against the high base of biodiesel sales last year. In addition, sales were likewise affected by scheduled plant maintenance during the period, softer fuel demand amid elevated pump prices, and heightened geopolitical tensions, which added on to already bleak market conditions.
With the Batangas plant now fully operational, the Chemrez group is well positioned to serve a broader global customer base and support the continued expansion of its higher value-added, sustainable product portfolio. Backed by its expanded production capacity and diversified product offering, the company remains optimistic about its medium-term growth prospects and
profitability.
Specialty Plastics
Specialty Plastics continued to deliver a solid performance in 9M26, with earnings increasing 30% YoY, driven by 5% volume growth and a 1.9-ppt increase in gross margins. While supply chain disruptions continue to remain a threat due to unresolved conflict in the Middle East, which could affect the availability of petroleum-derived raw materials used in the plastics industry, the company has successfully secured critical inputs and has maintained uninterrupted supply to customers. This reinforced D&L’s position as a reliable and trusted vendor partner in an increasingly challenging operating environment.
The segment’s highly technical and customized product portfolio, coupled with its ability to ensure consistent inventory availability during periods of market disruption, continues to differentiate the business and strengthen customer relationships. Over the longer term, sustained investments in research and development and a strong pipeline of new product innovations are expected to support further margin expansion and deepen customer engagement.
Consumer Products ODM
Consumer Products ODM saw its earnings grow by 3% YoY for the period as the Batangas plant continued to ramp up operations. The segment remains well positioned for sustained expansion, supported by additional capacity from the new facility and ongoing efforts to grow its export business. Export sales now account for 16% of total segment revenues, up from virtually zero five years ago, highlighting the company’s successful execution in expanding its presence in international markets. With ample production capacity and a growing global customer base, the segment is well positioned to sustain its growth trajectory in the years ahead.
-end-
D&L Industries is a Filipino company engaged in product customization and specialization for the food, chemicals, plastics and consumer products ODM industries. The company’s principal business activities include manufacturing of customized food ingredients, specialty raw materials for plastics, and oleochemicals for personal and home care use. Established in 1963,
D&L has the largest market share in most of the industries it serves, as well as long-standing customer relationships with the Philippines’ leading consumer and manufacturing companies. It was listed on the Philippine Stock Exchange in December 2012. For more information, please visit https://www.dnl.com.ph/investors/.
This press release may contain some “forward-looking statements” which are subject to a number of risks and uncertainties that could affect D&L’s business and results of operations. Although D&L believes that expectations reflected in any forward-looking statements are reasonable, D&L does not guarantee future performance, action or events.
INVESTOR RELATIONS CONTACT
Crissa Marie U. Bondad
Investor Relations Manager – D&L Industries Inc.
+632 8635 0680
crissabondad@dnl.com.ph / ir@dnl.com.ph